

Short answer
Federal rules do not set a cargo insurance minimum for a cargo van or sprinter hauling general freight. The only federal cargo coverage rule is for household goods movers. Your exposure for the freight comes from somewhere else: the carrier on the bill of lading is liable for loss or damage to it. On your own authority, that carrier is you, so the claim and the policy are yours, and the amount is set by the brokers and shippers you work with. On a lease, the shipment moves under the carrier’s authority, and your lease decides who provides cargo coverage and when a claim can be deducted from your pay.
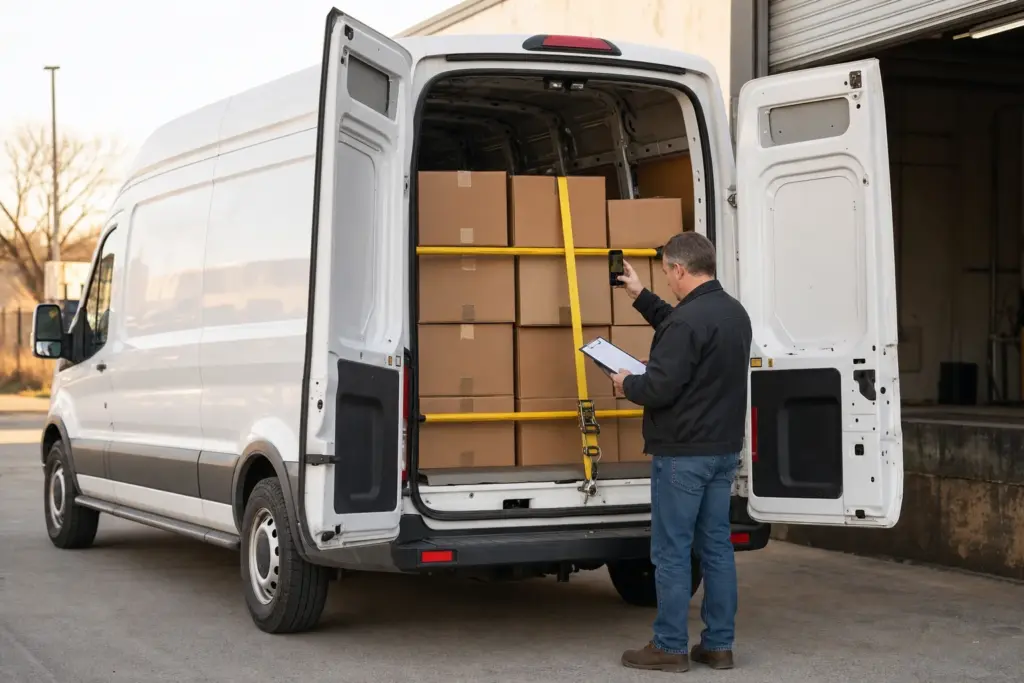
This guide is for cargo van and sprinter owners who want to know where cargo coverage sits in each way of working. We already covered the full insurance split on a lease for box truck owner-operators, including public liability, non-trucking liability and physical damage. Here we stay with one question: who answers for the freight inside your van, and who pays when it arrives damaged or does not arrive at all.
Is Cargo Insurance Required for a Cargo Van?
Not by federal rule, for general freight. For property carriers, Part 387 of the federal motor carrier rules sets public liability minimums, which protect the public from the way your vehicle is operated. Cargo security is a separate rule, and 49 CFR 387.303(c) sets it only for household goods motor carriers, at $5,000 per vehicle and $10,000 per occurrence. Section 387.301(b) applies that filing to household goods carriers. Nothing in Part 387 sets a cargo amount for a van hauling general freight.
That does not mean the freight is nobody’s problem. Under 49 U.S.C. 14706, a motor carrier must issue a receipt or bill of lading for property it takes, and the carrier is liable for the actual loss or injury to that property. The same section lets a carrier limit that liability to a value declared by the shipper or agreed in writing, if the value is reasonable. So the real cargo exposure is set by law and by your contracts, and a cargo policy is how a carrier pays for it.
The cargo amount you end up carrying comes from the brokers and shippers you work with. Each one can write its own cargo requirement into its carrier agreement. Ask for that number before you buy a policy, not after.

The Weight Line Changes Liability, Not Cargo
Vans sit on both sides of the 10,001 pound line, and that line matters for your public liability filing on your own authority. Under 387.303(b)(1)(i), a fleet made up only of vehicles rated under 10,001 pounds and hauling non-hazardous property needs $300,000. Under 387.9, a for-hire vehicle rated 10,001 pounds or more needs $750,000 for general freight.
Cargo coverage does not follow that line. Federal rules set no cargo amount for either side, and the value of what you haul has nothing to do with your van’s weight rating. A light van can carry a load worth more than a heavy one. When you price a cargo policy, start from the value of the freight you plan to haul and from what your brokers and shippers ask for.
| Your own authority | Leased onto a carrier | |
|---|---|---|
| Whose authority the load moves under | Yours | The carrier’s |
| Who receives a cargo claim | You, as the carrier | The carrier |
| Federal cargo minimum for general freight | None | None |
| Who sets the cargo amount | Your brokers and shippers, in their agreements with you | The carrier and its customers |
| Who provides the cargo policy | You | Whoever the lease names |
| How a claim can reach your pocket | Your deductible, plus anything the policy does not pay | Deductions from your settlements, only on the terms the lease states |
On Your Own Authority, the Claim Is Yours
With your own MC, you are the carrier on the bill of lading. A cargo claim comes to you, and federal claim rules in 49 CFR Part 370 tell you how to handle it:
- What counts as a claim. Under 370.3, a claim is a written communication that identifies the shipment, asserts liability and asks for a specific or determinable amount of money. A damage note on a delivery receipt, standing alone, is not a claim.
- Acknowledge it. Under 370.5, you acknowledge a proper claim in writing within 30 days of receiving it, unless you have already paid or declined it in writing. You open a separate file with its own claim number and record the date you received it.
- Investigate it. Section 370.7 calls for a prompt investigation, supported by the bill of lading and the invoice or another proof of value.
- Answer it. Under 370.9, you pay, decline or make a firm settlement offer in writing within 120 days. If you cannot, you tell the claimant in writing why, and repeat that every 60 days while the claim is open.
Your cargo policy pays the claim on its own terms, and the gap between those terms and the claim is yours. Before you buy, ask the agent:
- What is the limit per load, and does it match the amount in my broker and shipper agreements?
- What is the deductible on a cargo claim?
- Which commodities does the policy exclude?
- Does the policy cover theft, and under what conditions for a van that is parked or left unattended?
- Is the coverage written for the van I actually drive, and what do I do when I change vans?
Get the answers in writing, then send the certificate to each broker who asks. For everything else a van needs on its own authority, see our cargo van owner-operator requirements.
On a Lease, It Depends on the Carrier’s Program
When you lease your van onto a carrier, the load moves under the carrier’s authority. Federal leasing rules in 49 CFR 376.12 give the carrier exclusive possession, control and use of the equipment for the length of the lease, and complete responsibility for its operation. A shipper or broker files its cargo claim with the carrier, not with you.
Whether the carrier’s cargo policy protects you is a separate question, and the answer is in the lease. Under 376.12(j)(1), the only coverage the lease must assign to the carrier is public liability. For any other insurance, the lease has to say who provides it, and if the carrier bills you for any of it, how much. Cargo coverage falls in that second group. Carriers set up their programs differently, so two leases can answer it in opposite ways and both follow the rule.
Three parts of 376.12 protect you when a cargo claim comes up on a lease:
- The deduction terms are written down. Under 376.12(j)(3), the lease must state the conditions under which cargo or property damage can be deducted from your settlements.
- You see the math first. The carrier must give you a written explanation and itemization of any cargo deduction before it takes the money.
- You can see the policy. Under 376.12(j)(2), if you buy coverage from or through the carrier, you can get a copy of each policy on request and a certificate showing the insurer, the coverage, your cost and the deductible you may owe.
Read the deductible as your real exposure on a lease. If the lease lets the carrier deduct a cargo claim up to the deductible, that amount comes out of your pay even though the policy is in the carrier’s name.
Questions to Ask a Carrier Before You Sign
- Does your cargo policy cover my van while I run under your authority, and does the lease say so?
- Is there a cargo insurance charge-back, and is the amount written in the lease?
- What is the cargo deductible, and under what conditions can you deduct a claim from my settlement?
- Which commodities or situations does your cargo policy exclude?
- Can I get a certificate for every policy I pay for through you?
Compare the answers across carriers the same way you compare pay. A higher share with a large cargo deductible can cost you more after one bad load than a lower share with a small one.
Moving From a Lease to Your Own MC
The carrier’s cargo program covers loads that move under its authority. Once you run under your own MC, any cargo coverage the carrier provided no longer stands behind your loads, and the claims process in Part 370 becomes your job. Line up your own cargo policy before your first load, and match its limit to the agreements of the brokers you plan to work with.
Ready to Compare Carrier Leases for Your Van?
Apply for free with your van details. No MC number is required to apply, and we’ll share your information with carriers that may match your equipment and qualifications.
Find Cargo Van Opportunities → Find Sprinter Van Opportunities →Frequently Asked Questions
Does FMCSA require cargo insurance for a cargo van?
Not for general freight. The federal cargo security rule in 49 CFR 387.303(c) applies to household goods motor carriers. The cargo amount for a van hauling general freight comes from the brokers and shippers you work with.
Does the carrier’s cargo insurance cover my van when I’m leased on?
It depends on the carrier’s program and your lease. Under 49 CFR 376.12(j)(1), the lease must say who provides any insurance beyond the carrier’s public liability, and how much the carrier charges back for it. Check the lease for cargo coverage by name.
Can a carrier deduct a cargo claim from my pay?
Only on the conditions the lease states. Under 49 CFR 376.12(j)(3), the carrier must give you a written explanation and itemization before it makes any deduction for cargo or property damage.
How do I find cargo van or sprinter opportunities through Expedited Jobs?
Apply for free with your van details. No MC number is required to apply, and your information is shared with carriers that may match your equipment and qualifications.
Table of Content
- Is Cargo Insurance Required for a Cargo Van?
- Have a Cargo Van? Carriers Are Hiring.
- The Weight Line Changes Liability, Not Cargo
- On Your Own Authority, the Claim Is Yours
- On a Lease, It Depends on the Carrier’s Program
- Questions to Ask a Carrier Before You Sign
- Moving From a Lease to Your Own MC
- Frequently Asked Questions